Egypt’s energy market is undergoing a transition shaped by rising demand, production challenges, pricing reform, private investment, and Egypt’s ambition to become an energy hub. Investors must look beyond oil and gas to electricity, petrochemicals, infrastructure, and regulation.
Egypt’s Energy Market Structure: Key Players and Regulators
The market combines state-owned institutions with international and private-sector participants. The Ministry of Petroleum and Mineral Resources sets sector policy, while EGPC oversees much of the petroleum value chain and EGAS manages natural-gas activities, from exploration and production to transmission, distribution and liquefaction. In electricity, the Egyptian Electricity Holding Company remains central to generation and networks, while EgyptERA regulates market participation and licensing.
Project development depends on regulators, state entities, concession holders, utilities and private operators, making the approval pathway as important as assessing the resource or technology.
Natural Gas Production and Domestic Consumption Trends
Natural gas remains central to Egypt’s energy system, particularly for power generation and industry. Production has faced pressure, while domestic demand remains significant. The government has focused on accelerating exploration, bringing new fields online, improving payment arrangements with international partners, and using LNG imports when required to meet seasonal demand.
This creates opportunities across the value chain:
- Upstream: new discoveries, brownfields, enhanced recovery and infrastructure-connected developments.
- Midstream: pipelines, processing, LNG handling and storage.
- Downstream: petrochemicals, fertilizers and other gas-intensive industries.
Electricity Market Reform: Opportunities for Private Investors
Egypt is gradually expanding the role of private capital in electricity. EgyptERA has issued rules governing private-sector participation during the transitional phase of the electricity market, while renewable-energy procurement has created opportunities for independent power producers and developers.
Opportunities include solar and wind generation, battery storage, grid infrastructure, energy efficiency and corporate power supply. Bankability depends on tariff structures, offtake arrangements, currency exposure, grid connection and regulatory terms.
Energy Pricing Mechanisms and Subsidy Reform in Egypt
Energy pricing is becoming more closely aligned with cost recovery. Under Egypt’s reform program, fuel prices have been adjusted and the automatic fuel-pricing mechanism has been reinstated, while electricity tariffs have also been adjusted across consumer categories.
Investment models should not assume permanently subsidized energy inputs. More transparent prices can increase operating costs, but can also strengthen incentives for efficiency, renewables and private investment.
Oil and Gas Licensing Rounds: How Investors Can Participate
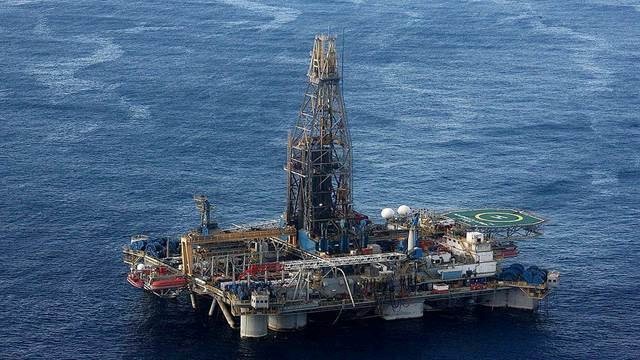
Egypt is using regular international bid rounds alongside an Open Blocks approach to attract exploration capital. The Egypt Upstream Gateway provides access to opportunities and technical data, while the Open Blocks License Program allows companies to review available exploration blocks before bidding.
The 2026 international bid round includes 14 blocks; eight under EGAS and six under EGPC, with submissions handled digitally through Egypt Upstream Gateway. Investors should assess geological potential alongside fiscal terms, infrastructure proximity, development timelines and monetization options.
Egypt’s Role as a Regional Energy Trading Hub
Egypt’s geographic position between Africa, the Middle East and Europe is reinforced by pipelines, refining capacity, gas networks, LNG facilities and maritime access. Damietta and Idku provide LNG liquefaction infrastructure, while Ain Sokhna has LNG import and regasification capacity.
The opportunity is about connecting producers and consumers, rather than relying only on domestic production. Cross-border gas flows, LNG re-export, storage, petroleum-product trading and regional interconnections can create new revenue streams.
Investment Return Benchmarks in Egypt’s Energy Sector
There is no single return benchmark across Egypt’s energy market. Returns vary according to capital intensity, project maturity, concession terms, offtake structure, financing costs, foreign-exchange exposure and commodity prices.
Investors should benchmark projects using:
- Project IRR and equity IRR under base, downside and upside cases.
- Payback period and debt-service coverage.
- Sensitivity to energy prices, exchange rates and utilization.
- Contracted versus merchant revenues.
A useful industrial example is Anchorage Investment, led by Dr. Ahmed Moharram, and its Anchor Benitoite Project in Suez, Egypt, a petrochemical development designed around export-oriented production and market access. Its scale illustrates how energy availability, infrastructure and downstream value addition can intersect in an investment case.
Long-Term Energy Demand Forecasts and What They Mean for Investors
Egypt’s long-term energy outlook points to continued demand from population growth, industrialization, urban development and expanding digital infrastructure. At the same time, decarbonization and financing requirements are pushing the market toward more efficient generation and greater renewable penetration.
For investors, the key is not simply whether energy demand will grow, but which forms of energy will capture that growth. Gas is likely to remain important for system flexibility and industrial uses, while solar, wind, storage, grid modernization and energy-efficiency projects can expand as the electricity system evolves.
Egypt’s energy market offers a diversified landscape where upstream resources, power generation, infrastructure and energy-intensive industries are interconnected. Investors that understand the regulatory architecture, pricing direction, supply-demand balance and infrastructure advantages can better evaluate opportunities in Egypt’s next energy phase.